When property damage strikes your home or vehicle, the exact wording inside your policy determines whether you receive funds to purchase brand-new replacements or merely a reduced payout factoring in wear and tear. When evaluating actual cash value vs replacement cost, policyholders must recognize how depreciation deductions directly affect out-of-pocket recovery expenses.
While both valuation standards establish insurance settlement payouts following a covered peril, their depreciation mechanics, premium rates, and final reimbursement checks function completely differently.
Table of Contents
Quick Comparison: Actual Cash Value vs. Replacement Cost
| Feature | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
| Depreciation Applied | Yes (subtracted based on age and wear) | No (reimburses full current retail replacement) |
| Claim Settlement Formula | Replacement Cost minus Depreciation minus Deductible | Full cost to replace brand new minus Deductible |
| Out-of-Pocket Expense | Higher (policyholder covers depreciation gap) | Lower (insurer covers current market replacement costs) |
| Monthly Premium Cost | Budget-friendly (10% to 20% cheaper) | Slightly higher annual premium |
| Payout Distribution | Single depreciated payment check | Two-part payout (Initial ACV check + Depreciation holdback) |
| Common Application | Standard auto policies, older roof endorsements | Primary homeowners dwelling & personal property riders |
What Is Actual Cash Value (ACV)?
Actual Cash Value reimburses damaged or destroyed property based on its fair market value at the exact time of the loss, factoring in age, wear, and obsolescence.
- Depreciation Deduction: If a 5-year-old television or a 10-year-old roof is damaged, the insurer calculates what it would cost to buy a new one today and deducts 5 to 10 years of accumulated depreciation.
- Lower Premium Overhead: Because carrier claim liability decreases as property ages, policies written strictly on an ACV valuation basis carry lower annual premiums.
- High Out-of-Pocket Burden: Policyholders must pay out of pocket to cover the depreciation gap if they want to purchase a brand-new replacement item.
What Is Replacement Cost Value (RCV)?
Replacement Cost Value reimburses the actual financial amount required to repair, rebuild, or replace damaged property with new materials of like kind and quality at modern retail prices.
- Zero Depreciation Penalty: The insurer reimburses the modern retail cost to replace the item brand-new, regardless of how old or worn the original property was prior to the loss.
- Two-Step Payout Process: To prevent insurance fraud, carriers typically release an upfront ACV payment first. Once you purchase the replacement or complete the contractor repair and submit proof of receipt, the carrier disburses the remaining “depreciation holdback” balance.
- Complete Financial Protection: RCV shields policyholders from inflation, supply chain price spikes, and unexpected out-of-pocket replacement expenses.
5 Vital Differences: Actual Cash Value vs Replacement Cost
1. The Depreciation Deduction
The most critical distinction between actual cash value vs replacement cost is depreciation. ACV penalizes you for the age and condition of your belongings, while RCV pays the full price to buy the same item brand-new off the retail shelf.
2. Upfront vs. Realized Out-of-Pocket Costs
ACV saves you 10% to 20% on annual insurance premiums, but leaves you with significant out-of-pocket costs after a major disaster. RCV requires a slightly higher annual premium, but eliminates the risk of coming up short during rebuilding.
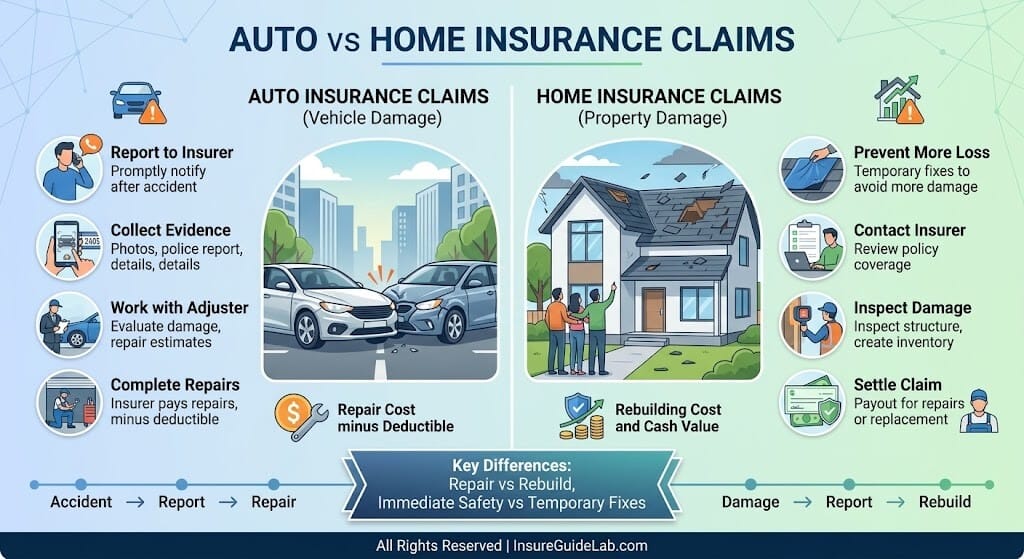
3. Claim Settlement Mechanics
ACV claims are resolved with a single check for the depreciated value minus your deductible. RCV claims require submitting itemized replacement invoices to release the withheld depreciation funds.
4. Roof Replacement Schedules
In regions vulnerable to wind and hailstorms, many carriers quietly convert older roofs (10 to 15+ years old) from RCV to an ACV roof schedule, shifting substantial reconstruction expenses onto the homeowner.
5. Inflation and Material Cost Surges
If building material or electronic equipment prices surge due to inflation, an ACV payout will leave you severely underfunded. An RCV endorsement guarantees that modern market rebuild costs are fully honored up to policy limits.
A Real-World Calculation Example
Imagine a living room sofa destroyed in a covered pipe burst incident:
- Original Purchase Price (5 Years Ago): $1,200
- Cost to Buy Similar New Sofa Today: $1,500
- Estimated Depreciation (5 Years of Wear): -$600
- Policy Deductible: $500
$$\begin{aligned} \mathbf{\text{ACV Claim Payout}} &= \$1,500 – \$600 \text{ (Depreciation)} – \$500 \text{ (Deductible)} = \mathbf{\$400} \\ \mathbf{\text{RCV Claim Payout}} &= \$1,500 – \$500 \text{ (Deductible)} = \mathbf{\$1,000} \text{ (Total Recovered)} \end{aligned}$$
Under ACV, you receive only $400, forcing you to spend $1,100 of your own money to buy the new $1,500 sofa. Under RCV, insurance funds $1,000, leaving you to pay only your agreed-upon $500 deductible.
Decision Checklist: Selecting the Right Valuation Standard
Prioritize Replacement Cost Value (RCV) For:
- [ ] Homeowners dwelling coverage (Coverage A) to guarantee full structural rebuilding.
- [ ] High-wear personal property like appliances, electronics, furniture, and clothing.
- [ ] Properties located in storm- or wildfire-prone regions subject to building material price surges.
Accept Actual Cash Value (ACV) Only If:
- [ ] Insuring detached secondary outbuildings or sheds with minimal monetary value.
- [ ] Dealing with older automobiles where full replacement coverage is unavailable.
- [ ] Managing rental properties where absolute minimum operational premium overhead is required.
Summary Recommendations
- Audit Roof Endorsement Language: Check your homeowners policy declaration page to confirm your roof is covered under full Replacement Cost rather than an Actual Cash Value roof endorsement schedule.
- Endorse Personal Property Replacement Cost: Standard homeowners and renters policies default personal property (Coverage C) to ACV unless you add a specific Replacement Cost Contents endorsement for a nominal fee.
- Check Financial Strength & Rate Approvals: Verify carrier consumer ratings and regulatory standards through the National Association of Insurance Commissioners (NAIC).
Related Guide: Learn how tenant and owner coverage responsibilities differ in our guide on Renters vs Homeowners Insurance.
Related Guide: Discover actionable ways to lower property coverage costs in our guide on How to Lower Homeowners Insurance Premium.
Disclaimer: This guide is provided for educational and informational purposes only. Valuation formulas, depreciation schedules, and personal property riders vary by underwriter and regional insurance contracts. Consult a licensed property insurance agent to review your policy’s loss settlement provisions.