When shopping for property or auto insurance, one of the most critical decisions involves selecting your claim reimbursement method. The fundamental choice between actual cash value vs replacement cost determines how much money you receive after a disaster, fire, or total loss.
Opting for the wrong valuation method can leave you with thousands of dollars in unexpected out-of-pocket expenses when rebuilding your home or replacing stolen possessions.
Quick Comparison: ACV vs. RCV
| Feature | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
|---|---|---|
| Depreciation Deduction | Yes (deducts wear and tear based on age) | No (pays modern market retail price) |
| Out-of-Pocket Burden | High (you cover the depreciation shortfall) | Minimal (only your deductible applies) |
| Annual Premium | 10% to 20% cheaper | Slightly higher annual cost |
| Best For | Tight budgets or older, detached structures | Primary homes, roof structures, and electronics |
| Claim Process | Single upfront settlement payment | Two-part payout (ACV first, depreciation later) |
What Is Actual Cash Value (ACV)?
Actual Cash Value (ACV) calculates the value of your damaged or destroyed property based on its replacement cost minus accumulated depreciation.
How ACV Calculates Losses:
- Depreciation Factors: Insurers evaluate age, physical condition, and expected lifespan.
- The Formula: $$\text{ACV} = \text{Replacement Cost} – \text{Depreciation} – \text{Deductible}$$
- Example: If a five-year-old television originally bought for $1,200 is destroyed, its current depreciated value might only be $400. Under ACV, the insurer pays $400 minus your deductible.
What Is Replacement Cost Value (RCV)?
Replacement Cost Value (RCV) pays the exact amount required to repair or replace damaged property with new items of similar kind and quality at current market prices, without deducting for depreciation.
How RCV Protects You:
- If that same $1,200 TV is destroyed and an equivalent new model currently costs $1,100, the RCV policy pays the full $1,100 (minus deductible) once you replace the item.
- It shields policyholders against inflation and rising construction supply costs.
Understanding Actual Cash Value vs Replacement Cost in Roof Claims
Roof replacement is the most frequent area where valuation differences trigger major claim disputes:
- Scenario: A windstorm destroys a 15-year-old asphalt shingle roof designed for a 20-year lifespan. Modern full replacement cost equals $12,000 with a $1,000 deductible.
- Under ACV: The roof has lost 75% of its lifespan. The insurer pays $3,000 minus $1,000 deductible ($2,000 payout), leaving the homeowner to pay $10,000 out-of-pocket.
- Under RCV: The insurer covers the entire $12,000 replacement cost minus the $1,000 deductible ($11,000 net payout).
5 Practical Factors When Choosing Coverage
- Age of the Home and Roof: Older properties benefit drastically from RCV to offset steep building material inflation.
- Personal Property Inventories: Electronics, furniture, and tools depreciate rapidly; insuring them under RCV prevents severe claim reductions.
- Cash Flow and Savings: If your emergency savings cannot cover major repair shortfalls, paying a higher RCV premium is the safer option.
- Outbuildings & Detached Garages: For older sheds or fences, ACV may offer sufficient protection at a lower price point.
- Mortgage Lender Mandates: Most mortgage lenders mandate RCV on the primary dwelling structure as a loan condition.
Summary Checklist
- [ ] Reviewed the declarations page of your home insurance policy to confirm dwelling coverage is set to RCV.
- [ ] Checked whether roof replacement terms include an ACV depreciation schedule.
- [ ] Created a digital home inventory of high-value electronics and appliances.
- [ ] Balanced higher deductibles to maintain affordable premiums with RCV coverage.
Related Guide: If you are dealing with vehicle damage instead of property loss, explore our breakdown on Gap Insurance vs New Car Replacement to protect against auto depreciation.
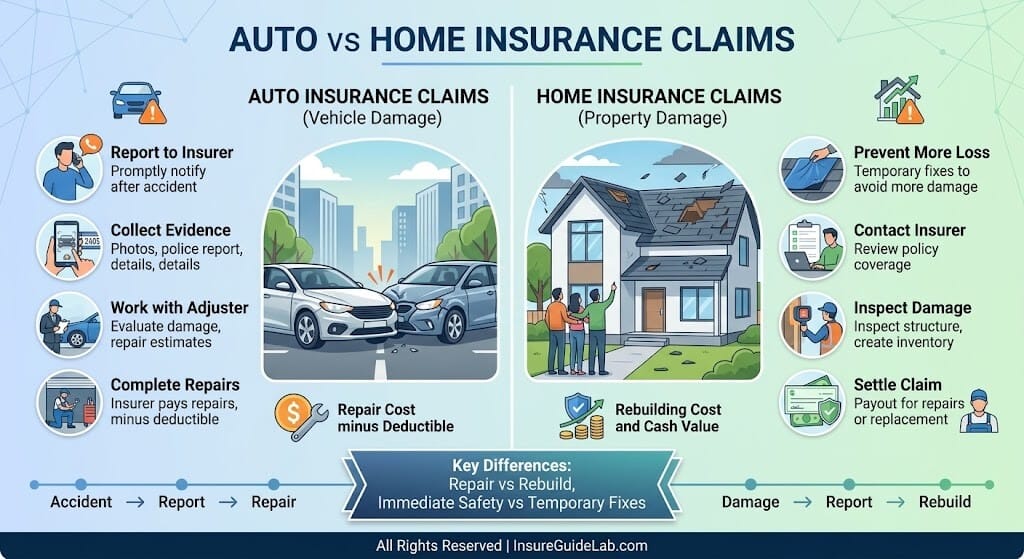
Related Guide: Learn the step-by-step claims filing strategy in our complete guide to How to File an Auto Insurance Claim.
Disclaimer: This guide is provided for educational and informational purposes only. Insurance endorsements, depreciation schedules, and valuation rules vary by carrier and state. Consult a licensed insurance advisor to review your specific policy declarations.